North India Statesman
[ad_1]
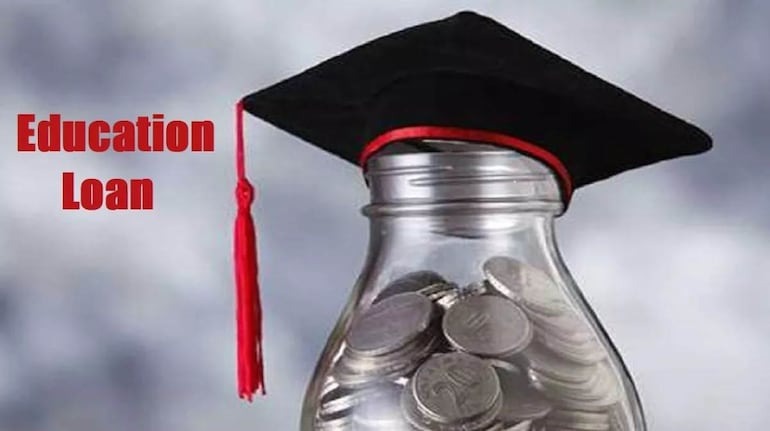
Taking education loan to get good and higher education has become very common and necessary in today’s time. It gives us a chance to fulfill our dreams. But once studies are over, this same loan can also become a huge financial burden. Many times, due to lack of proper information and planning, people keep paying its installments for years.
But with a little understanding and proper planning, you can lighten this burden considerably. Here are some smart strategies that will make your education loan journey easier.
1. Do ‘surgical strike’ on interest during studies itself!
Most banks start the EMI of the loan after completion of studies (called moratorium period). But during this period, interest continues to accrue on the principal amount of your loan and later this interest is also added to your principal amount, due to which your loan becomes bigger. If possible, keep paying only the loan interest amount every month during your studies. This small amount will significantly reduce the total cost of your loan in future.
2. Save tax, repay loan: Understand the magic of Section 80E
This is something that very few people know about. of Income Tax Act Section 80E You have repaid your education loan under Interest But you can avail tax exemption. The best thing about it is that there is no upper limit on it, that is, whatever interest you pay in a year, you can claim tax exemption on the entire amount. This is a great way to reduce the financial pressure on you.
3. Whenever you get a chance, attack ‘Extra’!
If you get a bonus in your job or have extra income from somewhere, instead of spending it, use it to pre-pay your loan. Even small additional installments can significantly reduce your loan tenure, saving you thousands and lakhs of rupees in interest.
4. Automate EMI, otherwise you will be hit by ‘late fees’
Missing even one EMI means late fees and a negative impact on your credit score. The easiest way to avoid this is Auto-Debit or ECS To use the facility. With this, your EMI will be automatically deducted from your bank account every month on the fixed date and you will never default. Also, keep a check on your expenses so that there is always enough balance in the account for EMIs.
5. In case of trouble, talk openly to the bank
While taking a loan, always compare the interest rates and terms of different banks. Maybe some bank is offering you a better deal. Apart from this, if you ever lose your job in future or face any other financial crisis, then instead of hiding from the bank, go and talk to them directly. Banks often face such situations Loan Restructuring They provide such facilities, which can give you relief for some time.
By adopting these methods, you can not only reduce the burden of education loan but can also make your financial future secure.