North India Statesman
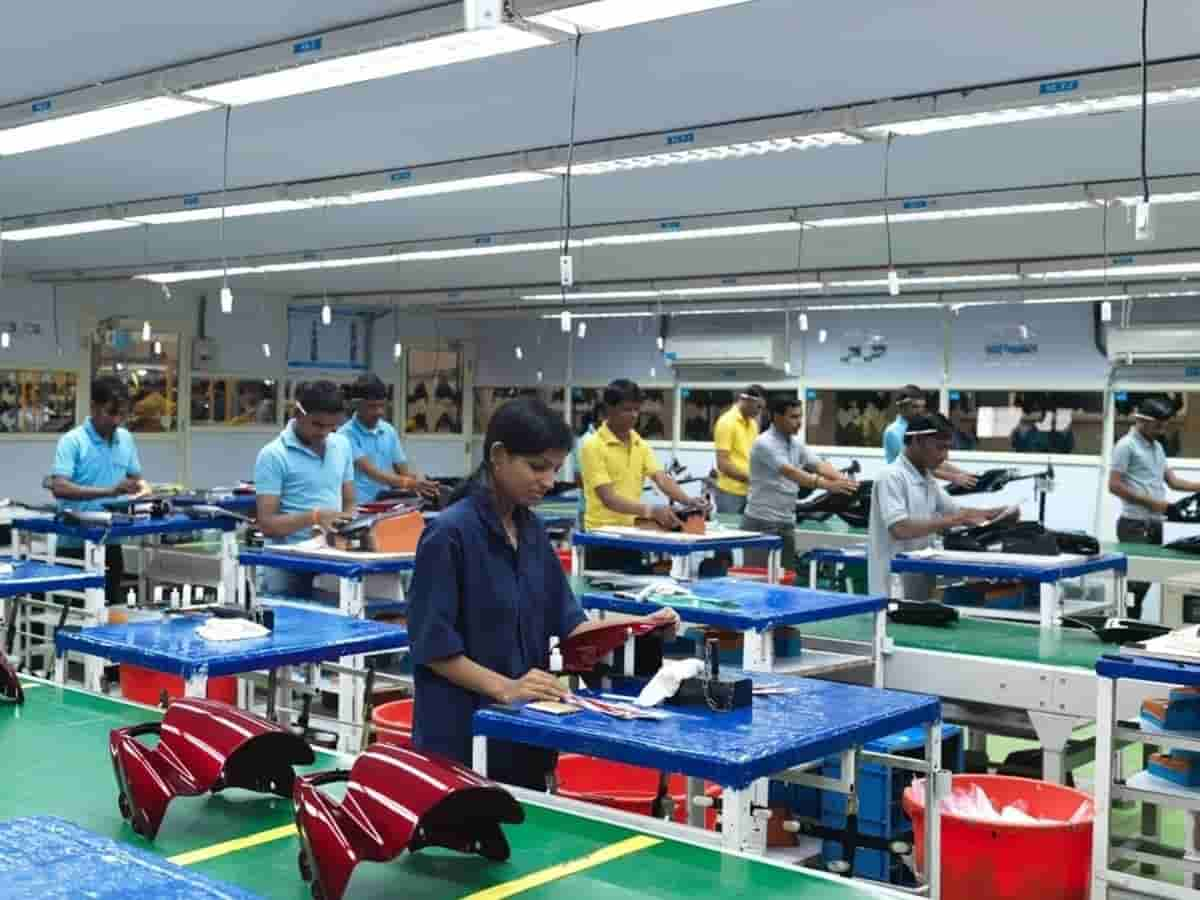
Investors who backed Pune-based automotive components manufacturer Belrise Industries during its May 2025 initial public offering at ₹90 per share are sitting on more than 160 percent returns, with the stock surging past the ₹235 mark on Dalal Street. Closing at ₹235.50 on the BSE on Tuesday, November 17, 2026—after touching an intraday high of ₹240.40—the mid-cap engineering counter has drawn renewed institutional attention following a strong September-quarter earnings beat and strategic diversification into precision electronics and aerospace. Global brokerage house Jefferies has reiterated its “Buy” rating on Belrise Industries while maintaining a target price of ₹280 per share, signaling roughly 19 percent further upside from current trading levels. For retail and institutional market participants tracking India’s manufacturing and electric-vehicle supply chain from Mumbai and Pune to Bengaluru and New Delhi, Belrise’s steady post-listing climb illustrates how earnings visibility and order-book expansion continue to reward patient equity investors.
Why Jefferies Sees Further Upside Toward ₹280
In its latest equity research note issued after Belrise Industries’ second-quarter financial disclosures, Jefferies highlighted the company’s successful push beyond traditional two-wheeler and four-wheeler chassis systems into higher-margin precision manufacturing. Specifically, Belrise recently secured a maiden Letter of Intent (LoI) to supply precision CNC fixtures to a key ecosystem partner of a major American smartphone maker—a customer Jefferies believes could be linked to Apple’s expanding supply chain. Alongside its entry into consumer electronics hardware, the company won an incremental track-beam order for a leading global commercial aircraft original equipment manufacturer (OEM), marking its first major order extension since acquiring UK-based aerospace supplier Chester Hall. Jefferies noted that these wins validate Belrise’s engineering capabilities and open multi-year revenue streams across automotive, aerospace, and electronics through FY29, even as the stock remains below its 52-week high of ₹268.
Inside Belrise Industries’ Strong Q2 FY27 Financial Performance
The fresh rally in Belrise Industries shares—which surged over 10 percent across two trading sessions on heavy volumes—was triggered by robust operational numbers for the quarter ended September 30, 2026 (Q2 FY27). According to exchange filings, the company’s consolidated profit after tax (PAT) jumped 25 percent year-on-year to ₹166.25 crore, up from ₹132.98 crore in the corresponding period of the previous fiscal year. Consolidated revenue from operations rose 16.7 percent year-on-year to ₹2,746.38 crore compared to ₹2,353.54 crore in Q2 FY26, supported by healthy demand across two-wheelers, three-wheelers, commercial vehicles, and passenger cars. Earnings before interest, tax, depreciation, and amortisation (EBITDA) climbed 11.6 percent to ₹330.62 crore. However, market analysts pointed out one key metric to monitor: consolidated EBITDA margin moderated by 60 basis points to 12 percent from 12.6 percent a year earlier, making margin stability an important watchpoint in upcoming quarters.
H-One India Merger and Belrise’s Journey Since the ₹90 IPO
Adding to investor optimism is the board’s approval of a fresh scheme of amalgamation between H-One India Private Limited and Belrise Industries Limited. Market watchers note that integrating H-One India—whose manufacturing capacity utilization was reported below 40 percent—provides Belrise with immediate room to scale domestic production and capture operational synergies without heavy fresh capital expenditure. Looking back at its public market debut, Belrise Industries’ ₹2,150 crore IPO was open for subscription from May 21 to May 23, 2025, with a price band of ₹85 to ₹90 per share. When the stock listed on May 28, 2025, at ₹98.50 on the BSE and ₹100 on the NSE, initial listing gains were a modest 9 to 11 percent. Over the subsequent 18 months, however, consistent quarterly execution, new OEM partnerships, and portfolio diversification propelled the share price past ₹235, turning an initial retail lot investment into more than 2.6 times its issue value.
Key Risks and What Retail Investors Should Keep in Mind
While brokerage targets like Jefferies’ ₹280 projection reflect confidence in Belrise Industries’ medium-term order book, financial planners advise retail investors in India to weigh both fundamentals and valuation before chasing sharp post-earnings rallies. Following its rapid surge on high trading volumes, the stock trades at a premium forward price-to-earnings multiple compared to several domestic auto-ancillary peers, leaving room for short-term profit booking or consolidation. Investors should also track whether operating margins recover above 12.5 percent as new electronics and aerospace contracts scale up, and monitor regulatory approvals for the H-One India merger. As always in equity markets, brokerage price targets represent institutional estimates rather than guaranteed outcomes, and individual investors should consult a SEBI-registered financial advisor and align stock exposure with their personal risk appetite.