North India Statesman
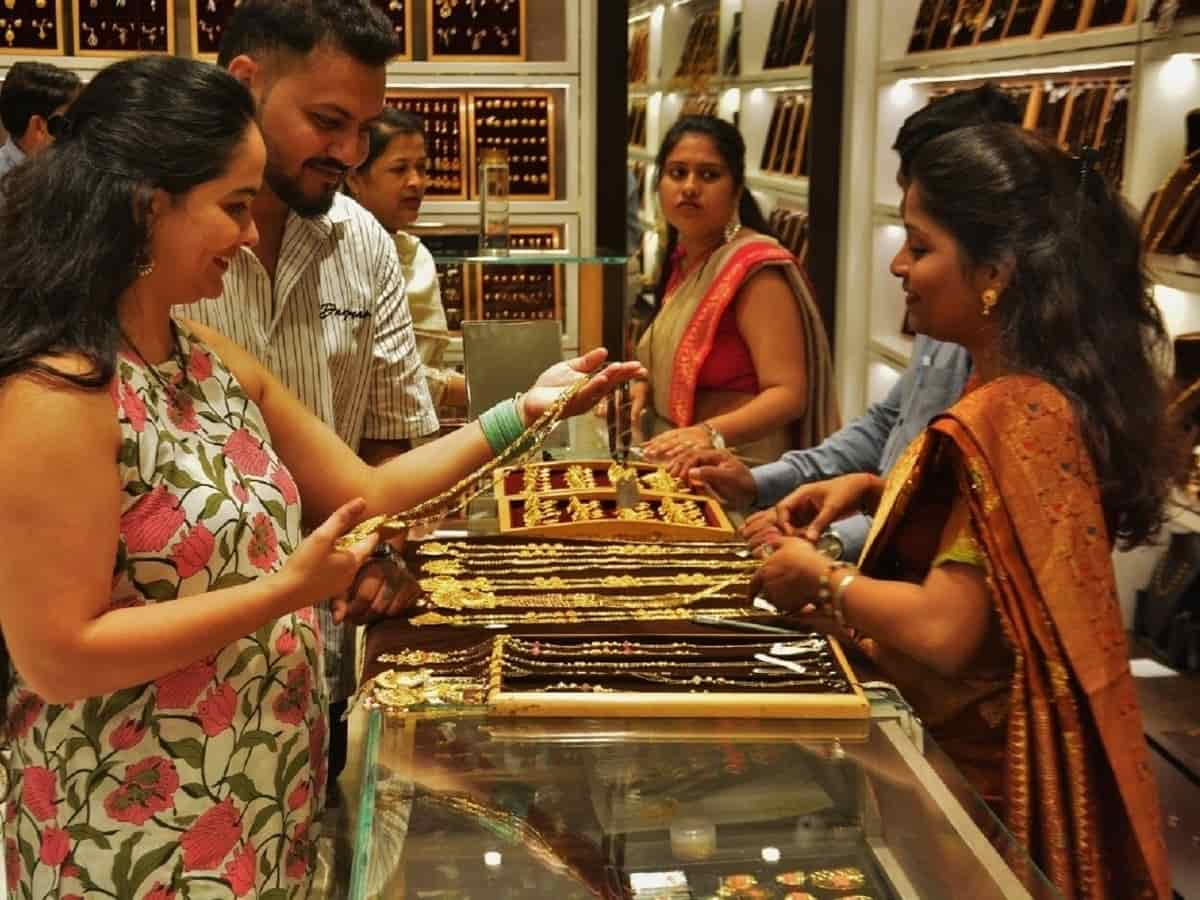
Every festive autumn, as the auspicious festival of Dhanteras arrives across India, millions of households visit their local jewellers to buy a token amount of precious metal. Rooted in the reverence of Lord Dhanvantari and Goddess Lakshmi, purchasing gold on this day is culturally viewed as an invitation to lasting prosperity, good fortune, and family security. While many buy gold coins, bars, or jewellery as sentimental heritage or ceremonial tradition, a retrospective look at the bullion market reveals an astonishing financial truth: those who invested in gold on Dhanteras a decade ago have witnessed an unprecedented wealth creation cycle. A modest lump-sum investment of ₹30,000 made on Dhanteras in 2016 has ballooned to approximately ₹1.41 lakh in 2026, delivering an eye-popping absolute return of nearly 370% and reaffirming gold’s uncontested stature as India’s ultimate safe-haven asset.
How ₹30,000 Turned Into ₹1.41 Lakh: Breaking Down the 10-Year Math
To understand the sheer magnitude of this compounding, consider the retail prices prevailing across major bullion hubs in late October 2016. On Dhanteras 2016, 24-karat pure gold (999 purity) traded at approximately ₹29,980 to ₹30,000 per 10 grams (one tola). An ordinary middle-class buyer allocating ₹30,000 walked out of the jewellery store with a clean 10-gram coin. Fast forward a decade: persistent geopolitical friction, currency realignments, and global de-dollarisation have propelled domestic 24-karat gold past ₹1,39,000 to ₹1,41,500 per 10 grams. That single 10-gram coin purchased for ₹30,000 is now valued at roughly ₹1.41 lakh. This represents a compound annual growth rate (CAGR) of approximately 16.7% over a ten-year stretch—handily outperforming bank fixed deposits, public provident funds (PPF), and matching the performance of blue-chip equity mutual funds, all while carrying significantly lower downside volatility.
Why Gold Surged: Geopolitical Headwinds, Central Banks, and Currency Factors
The journey from ₹3,000 per gram in 2016 to over ₹14,100 per gram in 2026 was not a fluke; it was powered by a perfect structural storm in macroeconomics. First, central banks worldwide embarked on an aggressive bullion-buying spree. The Reserve Bank of India (RBI), along with the People’s Bank of China and monetary authorities across Europe and the Middle East, diversified their foreign exchange reserves away from the US dollar and Western sovereign bonds, shifting hundreds of tonnes of physical bullion into sovereign vaults. Second, a relentless chain of global disruptions—ranging from pandemic shocks and supply chain breakages to prolonged regional conflicts and high worldwide inflation—ignited institutional safe-haven demand. When equity markets experienced steep corrections, global capital systematically retreated into the timeless security of gold. Third, the domestic rupee-dollar dynamic played an immense role for Indian investors. Because international bullion is denominated in US dollars, any depreciation of the Indian Rupee (INR) against the greenback acts as a natural booster for domestic gold prices. Even during phases when international gold prices traded sideways, Indian gold prices climbed steadily higher purely due to currency parity adjustments.
Physical Jewellery vs Digital Gold: Which Delivered Maximum Real Wealth?
While the raw bullion price soared by ~370%, the net return in an investor’s hands depended heavily on the vehicle chosen during that Dhanteras purchase.
-
Physical Jewellery: Buyers who purchased 22-karat ornaments in 2016 undoubtedly enjoyed their aesthetic and emotional value, but their monetary return was shaved by upfront making charges (typically 8% to 20%), 3% Goods and Services Tax (GST), and standard resale melt deductions during liquidation.
-
Gold Coins and Minted Bars: Investors who opted for hallmarked tamper-proof 24-karat coins from reputed jewellers bypassed heavy making deductions, preserving maximum physical weight and capturing almost the full capital gain.
-
Sovereign Gold Bonds (SGBs): The smartest financial move of the decade belonged to investors who bought Sovereign Gold Bonds issued by the Reserve Bank of India. Beyond tracking the domestic gold price step-for-step, SGBs paid an additional 2.50% annual cash interest credited directly to bank accounts. More importantly, capital gains on redemption at the end of their eight-year maturity were 100% tax-free, turning a ₹30,000 bond allocation into nearly ₹1.55 lakh in net, post-tax cash wealth.
-
Gold ETFs and Mutual Funds: Investors trading through demat accounts enjoyed high liquidity, paperless storage, and zero theft risks, paying nominal expense ratios while participating entirely in the price surge.
Local Bullion Markets: From Zaveri Bazaar to Aminabad, Festive Sentiment Runs High
The decade-long windfall has ignited electric festive sentiment across prominent traditional bullion centres in India. From the crowded historic alleys of Zaveri Bazaar in Mumbai and Dariba Kalan in Old Delhi to Johari Bazaar in Jaipur, T. Nagar in Chennai, and the bustling lanes of Aminabad and Chowk in Lucknow, buyers are flocking to retail showrooms. Regional trade bodies report that while high unit prices have led some retail buyers to opt for lighter grammage, the psychological trust in the yellow metal has never been stronger. Families are actively exchanging older, ancestral jewellery for fresh hallmarked pieces, while first-time millennial and Gen-Z earners are setting up automated monthly gold SIPs (Systematic Investment Plans) on digital investment platforms. What was once seen as an old-fashioned parental habit has transformed into a core portfolio diversifier for modern households.
What Every Buyer Should Keep in Mind Before Investing Today
For individuals looking to participate in the ongoing rally or initiate fresh allocations this festive season, discipline and verification are critical:
-
Insist on BIS 6-Digit HUID: If purchasing physical ornaments, never compromise on Bureau of Indian Standards (BIS) hallmarking featuring the unique 6-digit alphanumeric Hallmark Unique Identification (HUID) code. This guarantees verified purity (22K916 for 22-karat or 24K999 for 24-karat) and protects against under-karatage when exchanging.
-
Scrutinise Making Charges: For investment-oriented purchases, avoid intricate studded stones or high-wastage designs. Plain cast coins or simple bars keep wastage and overhead costs under 2% to 3%.
-
Maintain Portfolio Balance: Although gold has generated spectacular 16%+ annual returns over the past ten years, financial planners caution against putting all family savings into a single basket. Maintaining an allocation of 10% to 15% of your total net worth in precious metals provides the optimal hedge against inflation and equity drawdowns without sacrificing long-term compounding from enterprise growth.
As the lamps are lit and traders open their new ledgers this Dhanteras, the historic 10-year rally stands as a powerful reminder: in the landscape of Indian wealth creation, tradition and sound financial prudence often walk hand in hand.