North India Statesman
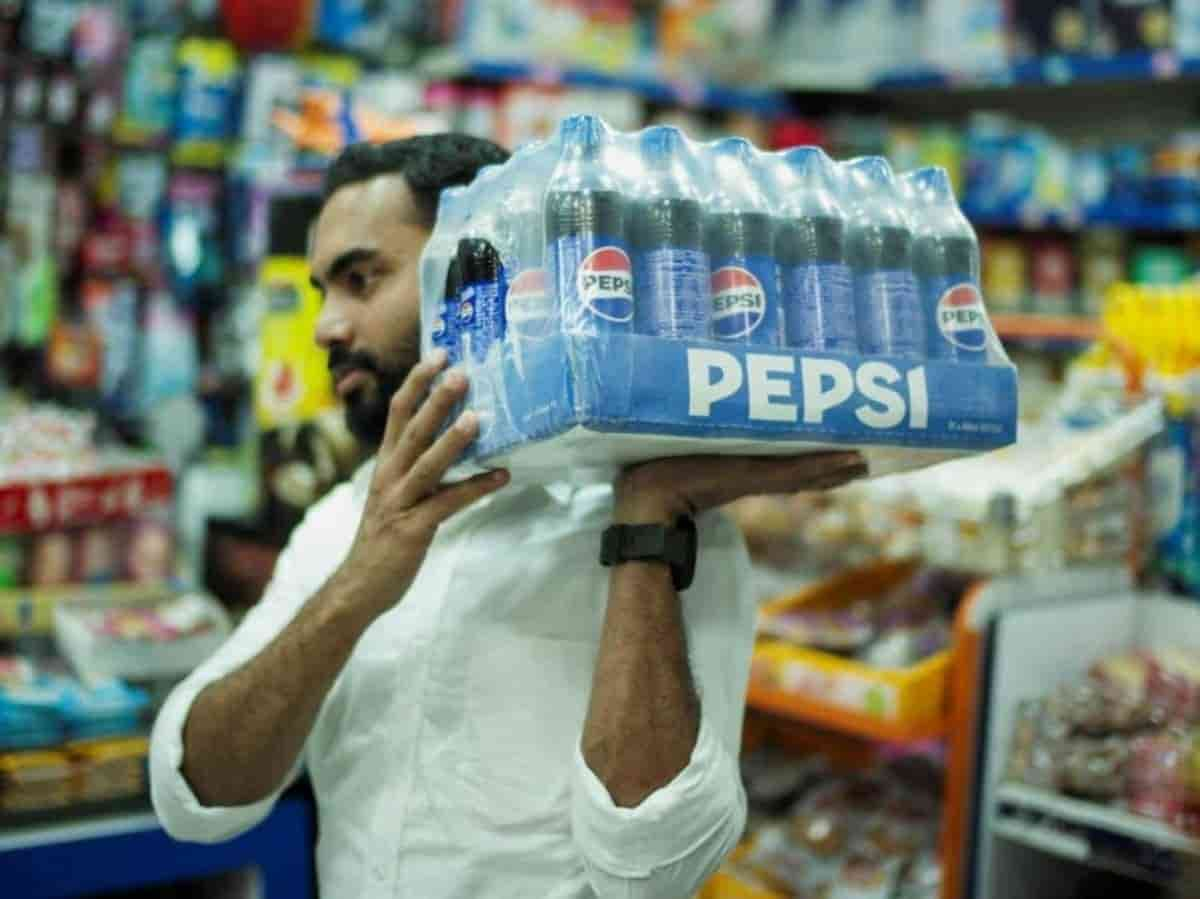
Varun Beverages Limited, one of the largest franchisees of PepsiCo globally, has delivered another strong operational performance, recording an impressive 14 percent year-on-year increase in consolidated net profit. The beverage giant, which accounts for a substantial share of PepsiCo’s beverage volume in India and key international markets, continues to demonstrate robust pricing discipline, distribution expansion, and product diversification across emerging consumption belts. Alongside the earnings surge, the board of directors has cleared a fresh dividend payout, rewarding long-term shareholders and reaffirming management confidence in structural cash generation. Leading equity research desks and domestic institutional brokerages have reaffirmed their bullish rating on the counter, raising forward target prices amid persistent rural penetration, extended chilling infrastructure, and sustained outperformance in energy drinks and packaged hydration segments.
Steady Volume Growth and Robust Operational Execution
The double-digit surge in bottom-line performance reflects operational resilience across core northern, central, and western Indian territories, compounded by strategic market entries in overseas markets across Africa and adjacent subcontinental geographies. Revenue from operations witnessed solid gains, propelled by double-digit volume expansion in carbonated soft drinks, packaged drinking water, and high-margin energy beverages like Sting. Even during off-peak seasonal windows, local consumer demand remained remarkably buoyant, bolstered by extended festive distribution channels and improved retail refrigeration in tier-two, tier-three, and rural retail outlets. Supply chain modernization, backward integration in preforms and closures, and disciplined cost governance enabled the bottler to insulate its operating margins from selective packaging and raw material input inflation.
Margin Expansion and Backward Integration Efficiencies
On the operational front, earnings before interest, tax, depreciation, and amortization reflected disciplined cost-control protocols and manufacturing efficiencies. The strategic alignment of automated bottling facilities, combined with in-house manufacturing of corrugated boxes, crowns, and preforms, shielded the company from freight shocks and volatile PET resin pricing cycles. The expansion of localized production hubs has structurally reduced transit lead times, allowing direct supply to high-consumption centers across Uttar Pradesh, Maharashtra, Rajasthan, Madhya Pradesh, and southern distribution corridors. This sharp logistical focus not only lowered freight overheads per case but also enabled higher inventory turns across regional retail touchpoints.
Dividend Announcement Reenforces Shareholder Wealth Creation
In line with its steady capital allocation policy, the board approved an interim dividend distribution, further strengthening the company’s reputation as a reliable dividend payer in the consumer goods space. The payout underscores healthy free cash flow conversion despite recurring capital expenditure dedicated to greenfield production plants, cold-chain assets, and foreign market consolidations. Investors have welcomed the management’s balanced approach of rewarding equity holders while simultaneously funding aggressive organic capacity additions and targeted inorganic acquisitions. The sustained return on equity and return on capital employed metrics continue to position the bottler among the most capital-efficient FMCG franchises in emerging markets.
Expanding Footprint Across International Frontiers
Varun Beverages’ growth narrative is increasingly being powered by overseas territory expansions. Recent forays and strategic market consolidations in African economies, including Zimbabwe, Zambia, Morocco, the Democratic Republic of the Congo, and South Africa via the acquisition of key distribution franchises, have diversified revenue streams beyond the Indian monsoon cycle. These high-potential African markets provide substantial per capita consumption headroom, enabling the company to replicate its proven Indian playbook of aggressive visi-cooler placement, affordable pack-size architectures, and robust secondary route-to-market networks. As these foreign facilities ramp up utilization, analysts anticipate significant operational synergies and accretion to overall consolidated margins over the medium term.
Product Portfolio Diversification Beyond Core Colas
While carbonated soft drinks such as Pepsi, 7UP, and Mirinda remain foundational volume drivers, the bottler’s intentional shift toward non-carbonated and value-added segments is yielding accelerated dividends. The meteoric ascent of Sting in the affordable energy drink space continues to outperform industry category benchmarks, capturing young consumer demographics across urban metros and semi-urban transit hubs. Concurrently, dairy-based beverages, value-added fruit juices, sports hydration brands like Gatorade, and packaged drinking water brand Aquafina are widening the company’s retail footprint into healthier and round-the-clock consumption occasions, dampening weather-induced seasonality risks.
Street Sentiment and Brokerage Outlook
Institutional market analysts and retail market watchers maintain an overwhelmingly positive bias on the equity, citing clear revenue visibility, relentless market-share gains from unorganized players, and consistent execution track records. Equity research analysts highlight that the aggressive capital investment in new manufacturing facilities ahead of peak summer seasons positions the bottler to capture unexpected spikes in seasonal demand without experiencing supply bottlenecks. Target prices set by prominent domestic and global brokerages indicate healthy double-digit upside potential, supported by steady compounding, expanding free cash flows, and defensible economic moats in distribution logistics.