North India Statesman
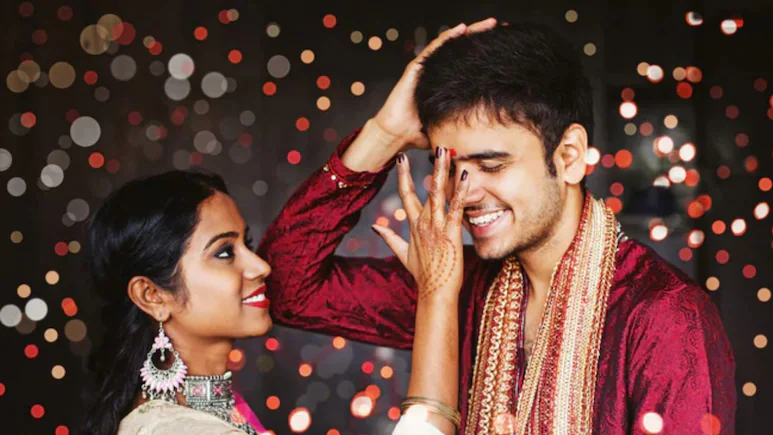
The festive season brings warmth, family reunions, and exchange of love across households. As celebrations for Bhai Dooj 2026 unfold across India on November 11, millions of brothers express their gratitude and affection by giving cash gifts, digital money transfers, or financial assets to their sisters. While monetary support and cash gifts are deeply tied to festival traditions, high-value financial transactions carry specific legal and regulatory obligations under Indian tax laws. Understanding how the Income Tax Department views financial exchanges between family members helps ensure that your celebration remains joyful and compliant with tax laws.
Section 56(2)(x) Income Tax Exemption for Siblings Explained
Under Section 56(2)(x) of the Income Tax Act, any sum of money or property received by an individual without adequate consideration is generally treated as taxable income under the head “Income from Other Sources”. However, the tax framework explicitly creates an exception for money received from specified relatives. Under the legal definition of “relative,” real brothers and sisters (siblings) are fully covered.
This means if a brother transfers a monetary gift to his sister—or vice versa—the entire principal amount is 100% tax-free in the hands of the receiver, regardless of the occasion or the total valuation. Whether you gift ₹10,000, ₹50,000, or even ₹5 lakh on Bhai Dooj 2026, the recipient does not have to pay income tax on the gifted sum. Unlike gifts received from friends or distant acquaintances—which trigger taxation if the aggregate value exceeds ₹50,000 in a financial year—monetary gifts between real siblings carry no upper ceiling for income tax exemptions.
Cash Restrictions and Section 269ST Penalties You Must Avoid
While monetary gifts from siblings are exempt from income tax, the mode of transfer introduces strict legal boundaries that taxpayers must follow carefully. Under Section 269ST of the Income Tax Act, no individual is permitted to receive an aggregate amount of ₹2 lakh or more in physical cash from a single person in a single day or for a single event/occasion.
If a brother gives his sister ₹2 lakh or more in physical paper cash as a festival gift, it violates Section 269ST, exposing the recipient to a 100% penalty under Section 271DA (or Section 451 under revised tax codes). The penalty amount equals the exact cash sum received. Therefore, high-value festive gifts should always be made using traceable, electronic, or banking channels—such as Unified Payments Interface (UPI), National Electronic Funds Transfer (NEFT), Real Time Gross Settlement (RTGS), Immediate Payment Service (IMPS), or an account-payee cheque. Banking transfers maintain a verifiable electronic paper trail, completely safeguarding both parties from cash restriction violations while preserving tax-free status.
Tax Implications of Investing Gifted Money and Clubbing Provisions
A common area of confusion during festival gift planning involves the income generated after the cash transfer is complete. Even though the initial monetary gift transferred to an adult sister is tax-free, any future yield earned by investing that money becomes taxable. For example, if a sister deposits a gifted ₹5 lakh into a high-yield Fixed Deposit (FD), mutual fund, or equity market instrument, the interest income, dividends, or capital gains accrued will be added to her total income and taxed according to her applicable income tax slab rates or capital gains rules.
Taxpayers must also account for Income Tax Clubbing Rules (Section 64) when transferring funds to minor siblings or spouses. If a gift is made to a minor sister, any income generated from that gifted capital will be clubbed with the income of the parent who earns a higher total income. For major (adult) siblings, clubbing provisions do not apply, and the recipient remains solely responsible for reporting subsequent investment earnings.
Essential Documentation and Reporting Practices for Large Gifts
Although genuine gifts between siblings do not trigger tax liabilities, high-value bank transfers can occasionally attract attention from tax authorities during routine processing or computerized risk-based scrutiny. To ensure complete peace of mind, siblings exchanging large sums of money should maintain proper documentation.
-
Gift Deed: For substantial monetary sums (typically exceeding ₹1 lakh to ₹5 lakh), executing a simple Gift Deed on stamp paper detailing the names, PAN details, relationship of donor and recipient, and explicit confirmation that the sum is given out of natural love and affection prevents future tax disputes.
-
Bank Statements: Retain bank transaction receipts or statement copies highlighting the exact debit and credit entries to verify the source of funds.
-
ITR Disclosure: The recipient should disclose large exempt gifts under the “Exempt Income” schedule while filing their annual Income Tax Return (ITR). Reporting exempt transfers ensures transparency with the Income Tax Department and prevents unexplainable wealth queries down the road.